


Throughout Summer 2026, news outlets have been dotted with headlines like these:
‘This bargain is eroding’: Inside the youngest generations’ view of the American Dream (CNBC, June 2026)
Young people are rejecting boomers’ view of the American dream (USA Today, June 2026)
Gen Z is working hard, but the economy is putting the American dream out of reach for many (FOX Business, July 2026)
The new American dream: Having parents who can help pay for it (CNN, July 2026)
The stories stem from a survey and report conducted by research consulting firm Simon-Kucher, published as the 2026 New American Dream Study. The report concludes that the American Dream is still alive, but it is no longer defined by one standard formula.
Based on a nationally representative survey of 5,000 U.S. adults, the report finds that traditional markers such as homeownership, family, hard work, and financial stability still matter, but younger generations are redefining success in broader, more personal terms. A major theme is the widening generational divide in how success is understood. Baby Boomers tend to anchor the Dream in stability and security, especially retirement, homeownership, and financial independence, while Gen Z and Millennials place more value on flexibility, personal freedom, experiences, community, and meaningful living.
The report stresses that younger people are not rejecting the American Dream; instead, they are adapting it to fit a more uncertain economic and social reality. The study also shows that the path to achieving the Dream feels increasingly unclear. No single route — whether college, entrepreneurship, skilled trades, public service, or corporate advancement — emerges as the dominant path forward. At the same time, most respondents believe key milestones such as owning a home, retiring early, and becoming financially independent are harder to reach than they were for previous generations. High living costs are the most common barrier, with younger adults also reporting job insecurity, debt, limited opportunities, and lack of confidence or skills as major obstacles.
Financial wealth is still seen as the clearest sign of status, and personal finances strongly shape whether people feel secure or successful. Yet the purpose of money is shifting: for many Americans, especially younger ones, it is less about visible wealth and more about maintaining stability, preserving quality of life, and keeping future options open. This helps explain why experiences now outweigh possessions across generations, and why Gen Z and Millennials are more likely to sacrifice long-term savings or take on debt to support their present-day lives.
Dreams Delayed
We wanted to understand how the idea of the American Dream is evolving. The findings are clear: for many, owning a home isn’t just a goal, it’s still the foundation for everything else. It’s just coming later in the game.
Nearly 1 in 5 aspiring homeowners (18% each) are putting off marriage or having children until they own a home.
17% (each) are delaying career changes or even getting a pet.
15% are waiting to start a business/go self-employed.
For younger generations, the impact is even more pronounced. 84% of Gen Z (ages 18-28) aspiring homeowners are postponing at least one major life decision until they can afford to buy, and nearly a third (29%) are delaying having children. Sixteen percent of respondents even said they were delaying living independently at all, in order to save for a home.
State-Level Data
If Millennials and Gen Z feel that the dream of home ownership is disappearing over the horizon, the data bears that out. Home prices in state after state are running up faster than wages can keep pace.
Open the Books examined a decade worth of public data comparing the change in state-by-state median household incomes (U.S. Census Bureau) with the home price index (HPI) which is tracked and tabulated by the Federal Housing Finance Agency (FHFA).
In all 50 states the average home price grew faster than median household incomes during the 10-year window we examined, which was 2015 to 2024. That difference in the rate of growth is what we’re calling the Affordability Gap.
In all but two states there was a double-digit Gap over the course of a decade. Louisiana experienced the least severe Affordability Gap with home prices (+39.99%) outpacing household wages (+33.37%) by just 6.62 points. Just ahead of it was West Virginia with a 9.93-point affordability Gap.
All 48 other states had double-digit affordability gaps.
The affordability gap topped 50 points in 17 states including many of the most populous.
In 14 states home prices rose more than 100% over the course of a single decade.
Under The Hood Roof
One might imagine affordability gaps uniformly higher in wealthy states with high taxes and high regulations while the American dream was within bettter reach in places with smaller government and lower barriers to entry for business. Instead the data reveals a more complex picture. Factors like economic dynamism versus relative stagnation and, at their tail end, the effects of Covid-related migration, ostensibly play a part — in addition to and in tandem with the more fundamental factors that allow for economic and wage growth.
The states with the top 10 highest Affordability Gaps are in fact geographically diverse and ideologically moderate or conservative. The top 10 were: Idaho, Florida, Utah, Tennessee, Arizona, New Hampshire, Nevada, Maine, and Washington state.
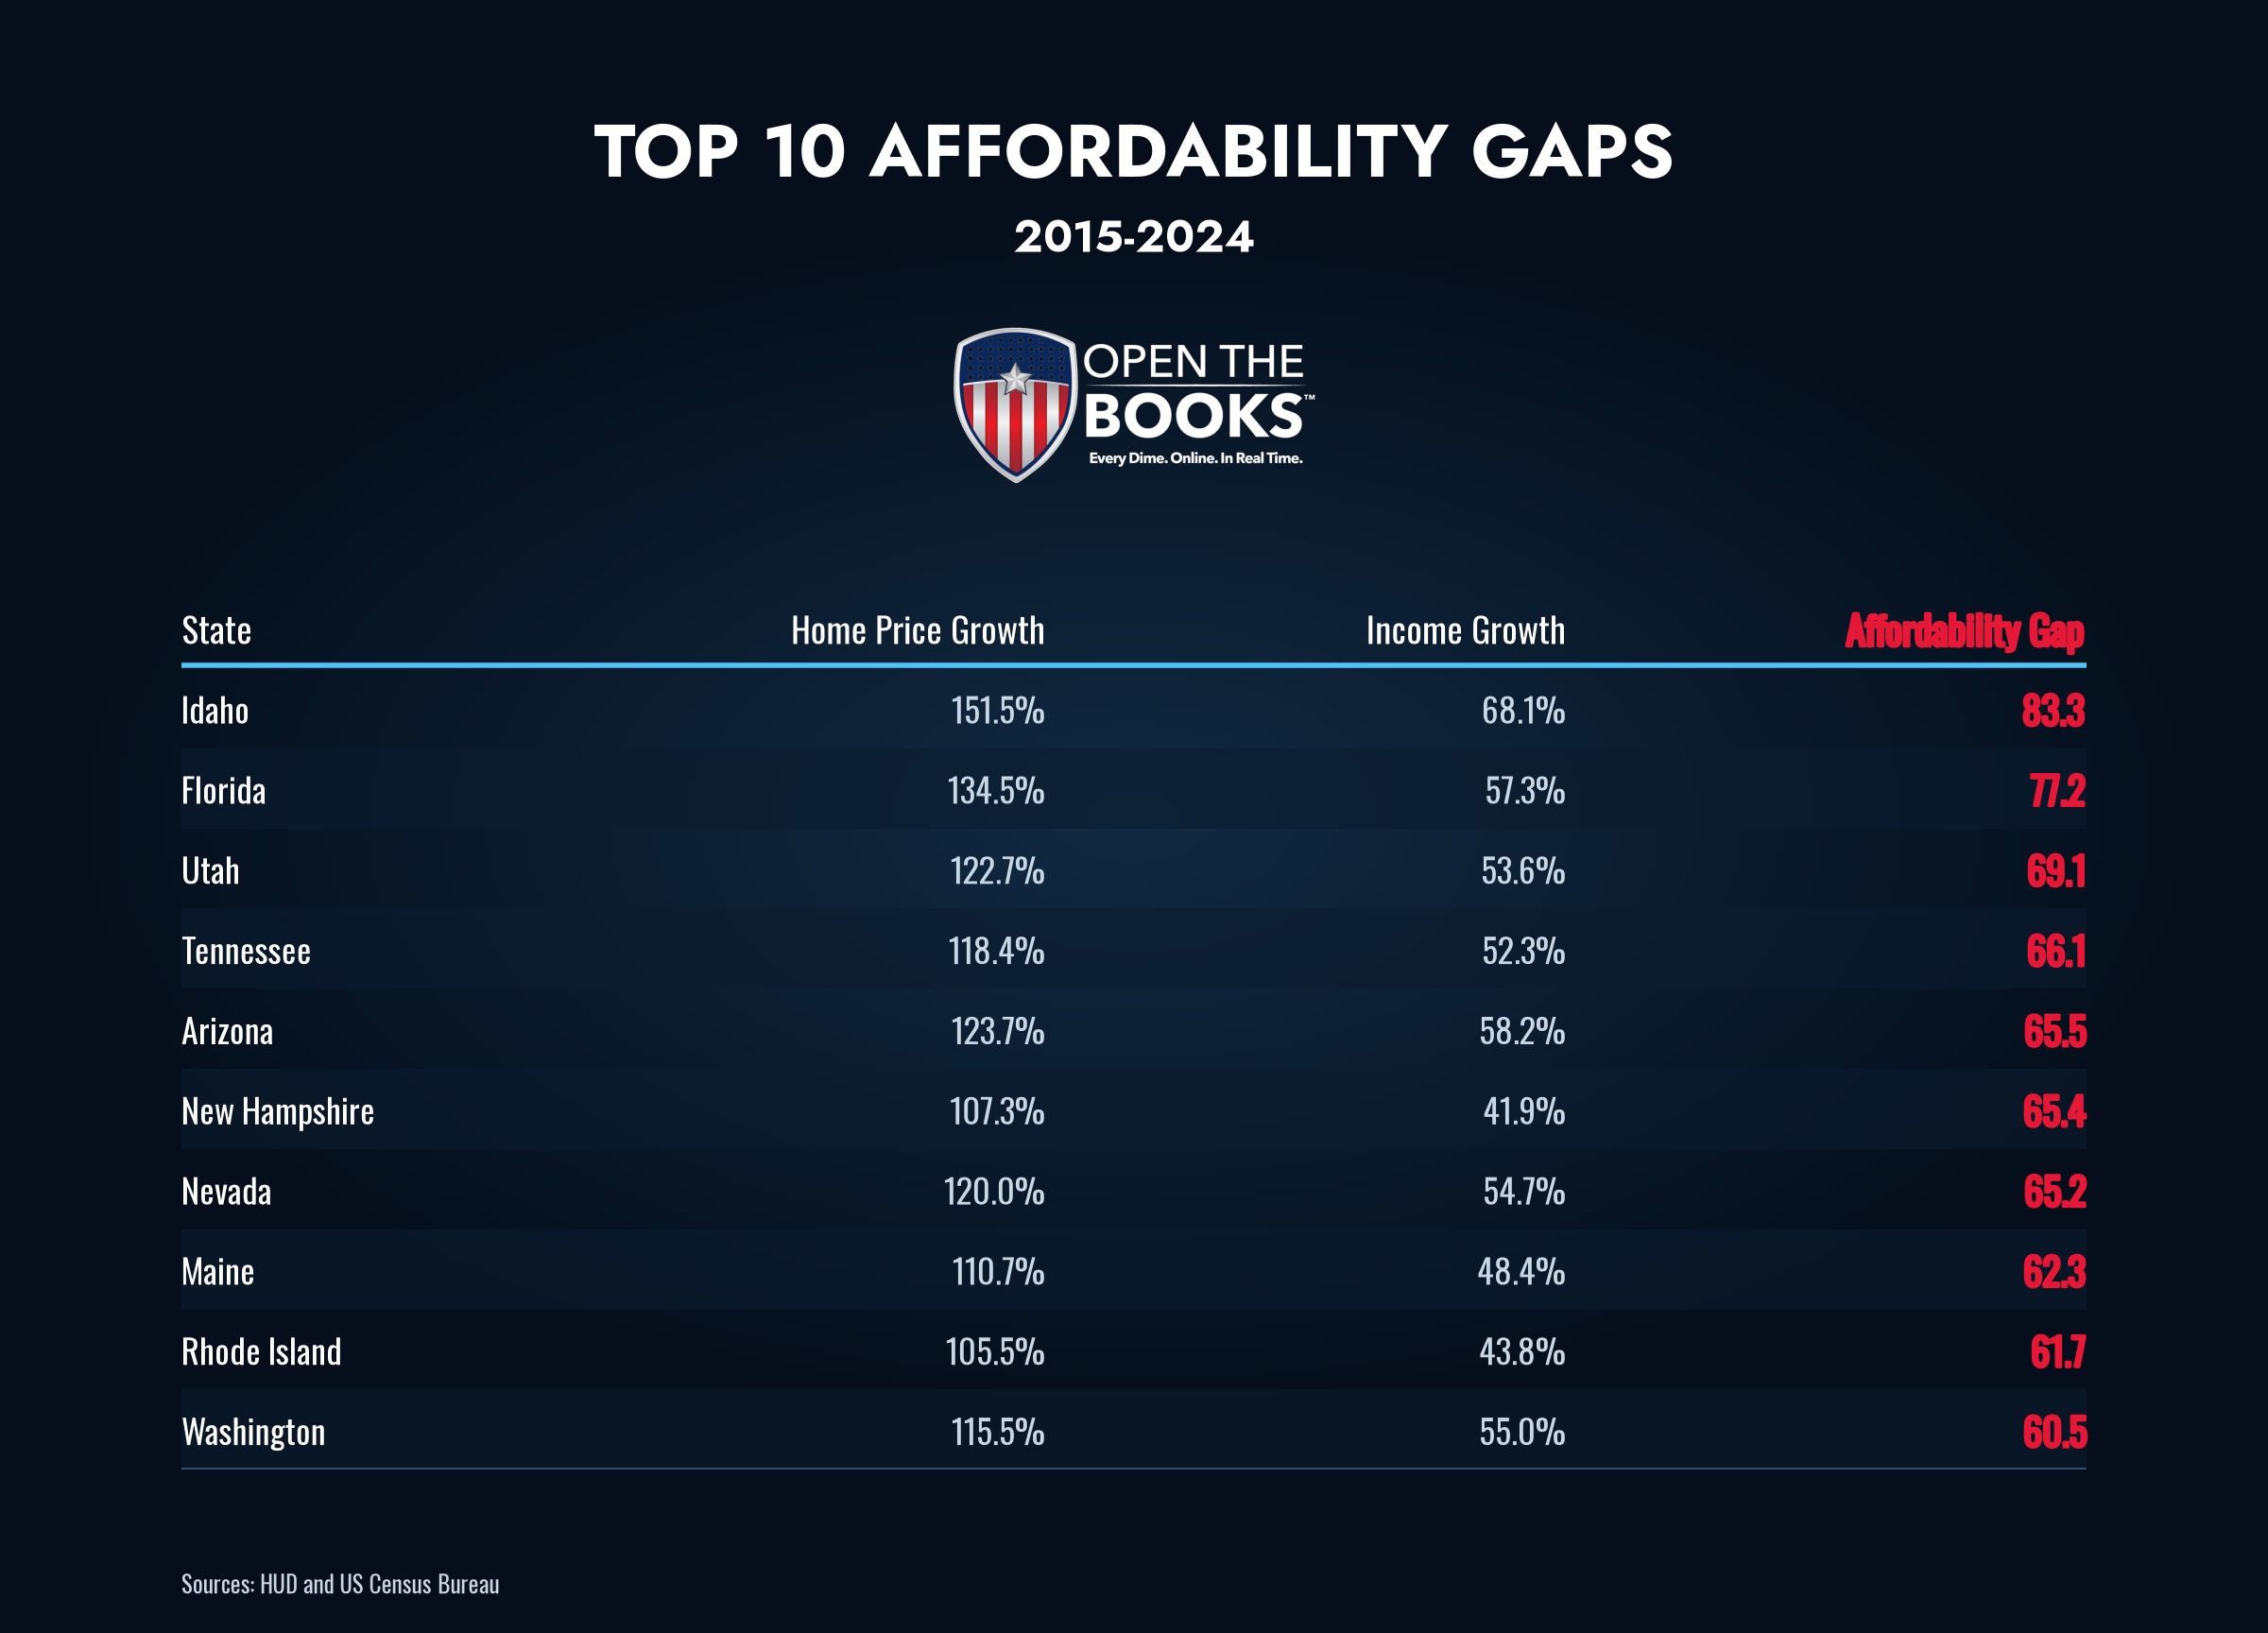
A couple of factors become apparent. Some of these states made headlines for massive influxes of Americans leaving big cities at the height of the Covid pandemic emergency. They’re also states that have become known for having friendly environments for businesses and individuals. Idaho, Florida, Nevada and Tennessee, along with Arizona, all became known as low-tax, lower-density havens during the Covid crisis and the ensuing inflation emergency.
In Idaho, the state with the highest Affordability Gap at 83.33%, home prices exploded faster than anywhere else in the country — 151.46% over the course of 10 years. Despite the Affordability Gap it created there are also signs that Idaho’s economy has begun racing to keep up. The state had the number one growth in median household income from 2015 to 2024. Households earned 68.13% more over the decade.
Home prices in Idaho also started relatively modest. The average home price in 2015 was $332,180. That figure skyrocketed by 2024 when an average priced home would run you over $835,000. This is thanks in part to Hollywood celebrities like Kim Kardashian, Clint Eastwood and Jimmy Kimmel, all of whom have purchased homes in Idaho. And as a rising tide lifts all boats, millionaires and billionaires in the area, the ensuing home value appreciation, and new labor demand are all conspiring to create more potential local wealth.
Close behind was Florida, a vacation destination of another kind, which also experienced a housing boom during Covid. Prices grew 134.47%, creating an Affordability Gap of 77.19 points. Actual home values resembled Idaho as well. An average home in 2015 costs $348,000, rising to $816,000 by the year 2024. By contrast, a state like California, which has drawn huge amounts of attention for its housing affordability problems and homelessness crisis in major cities, had a lower Affordability Gap (27.22 points). That gap was not narrowed by huge wage growth, though. California had a middling 55.27% rise in median household income over the decade. Instead, prices were comparatively stagnant. Average home prices grew 82.49%, comparable to states like New York, New Jersey and Kansas — and little more than half of market-leading Idaho. That figure also put California 52 points behind Florida’s average home price growth over that decade.
The ten states with the smallest Affordability Gaps, while also ideologically diverse, all had softer home appreciation but also softer household earnings growth:
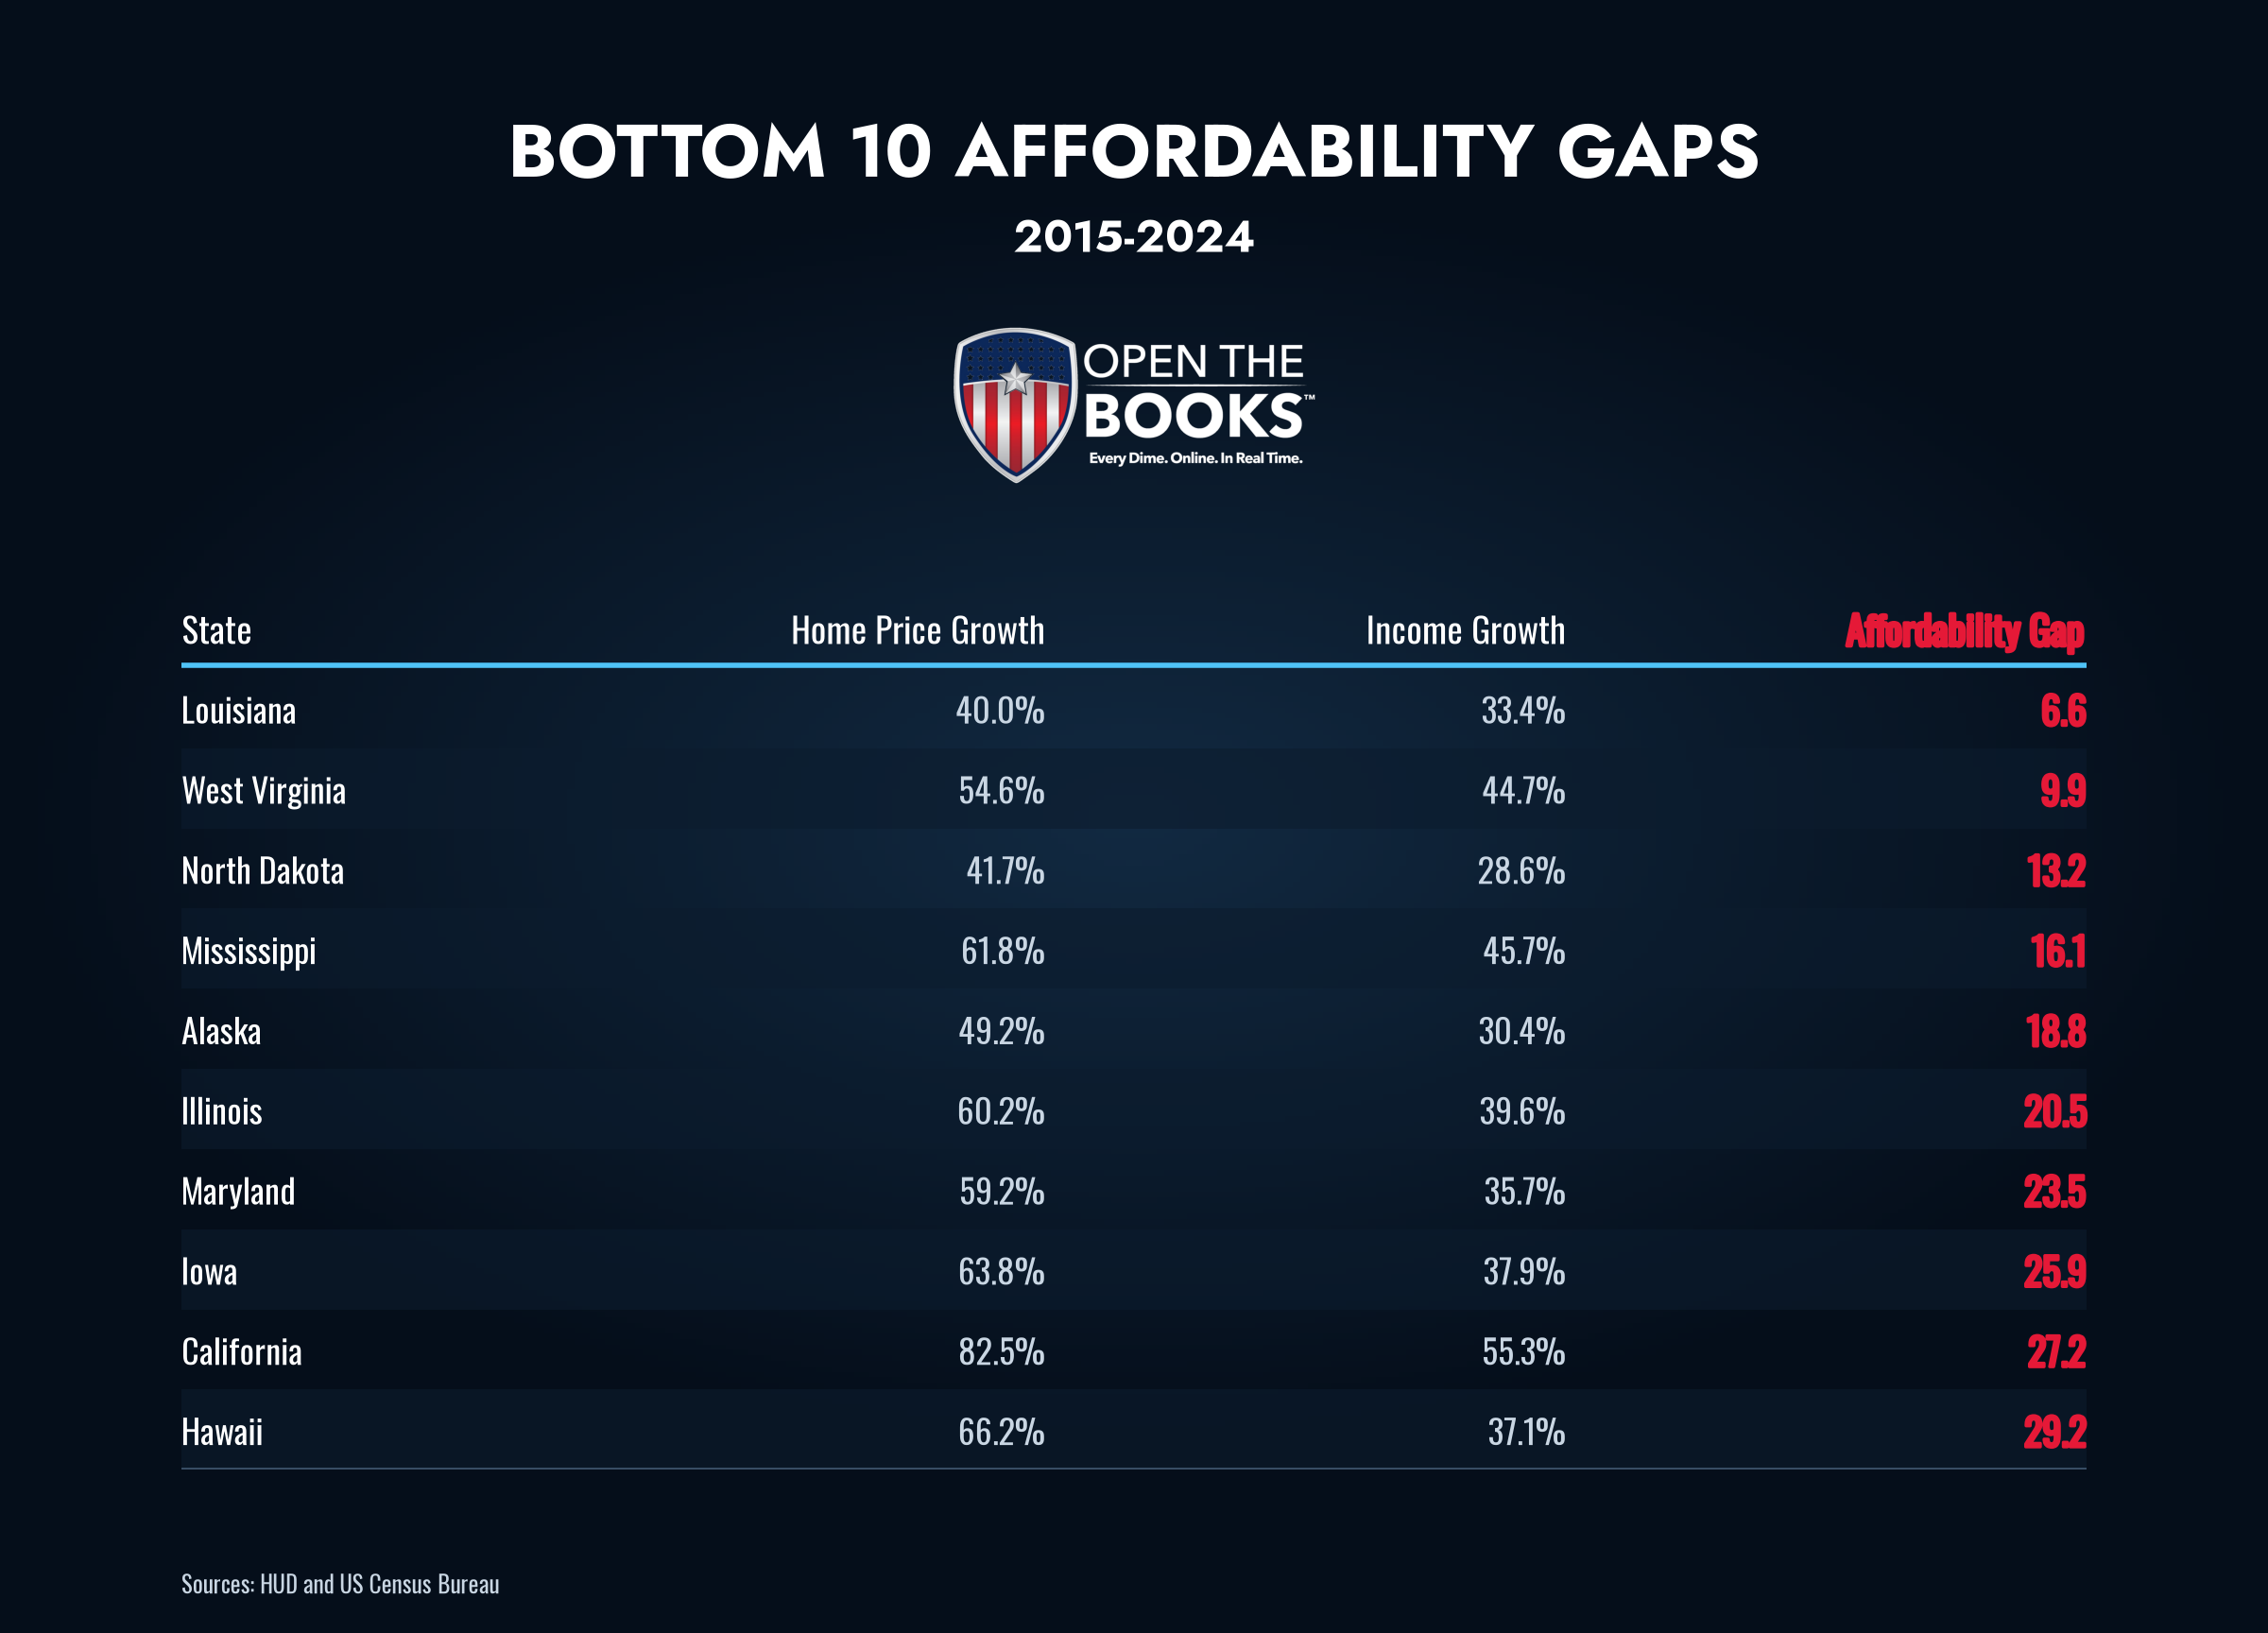
In summary, the traditional Red State-Blue State assumptions go out the window when we examine where wages have best kept up with home prices and where they’ve fallen the furthest behind. Several more factors are critical to get the full picture of housing affordability and the government’s role in it.
Government’s Role
Given its role at the heart of even this new, reordered American Dream, housing affordability deserves a deeper look. So, Open the Books is doing what it does best and examining the government’s role, assessing the publicly available data to offer insight into the ways our tax dollars are spent.
What does investment from the federal government do to help make the dream a reality?
Well, precious little if the most recent decade of data is any guide. Monetary policy of course plays a part, as the Fed sets interest rates that correlate with mortgage rates and tweak them based on economic indicators like inflation, employment and Gross Domestic Product (GDP). But when it comes to what Uncle Sam knows how to do best — or should we say, most — Washington has spent vast sums on the project of housing affordability.
The U.S. Department of Housing and Urban Development (HUD) spent nearly half a trillion dollars on it over the decade considered in this report — $460,282,287,603.59 to be more precise. That figure is spread across eighteen programs that capture the vast majority of HUD spending on affordability and low-income housing.
Much of the spending on a state-by-state basis amounted to less than $10 billion over the course of the decade; in a handful of states, it was up to $30 billion. In just a couple of outliers it was even more. New York had $58.93 billion pumped into it from HUD. California, the most extreme outlier, exceeded even that figure by tens of billions. From 2015-2014, those eighteen HUD programs injected $81.41 billion into the Golden State.
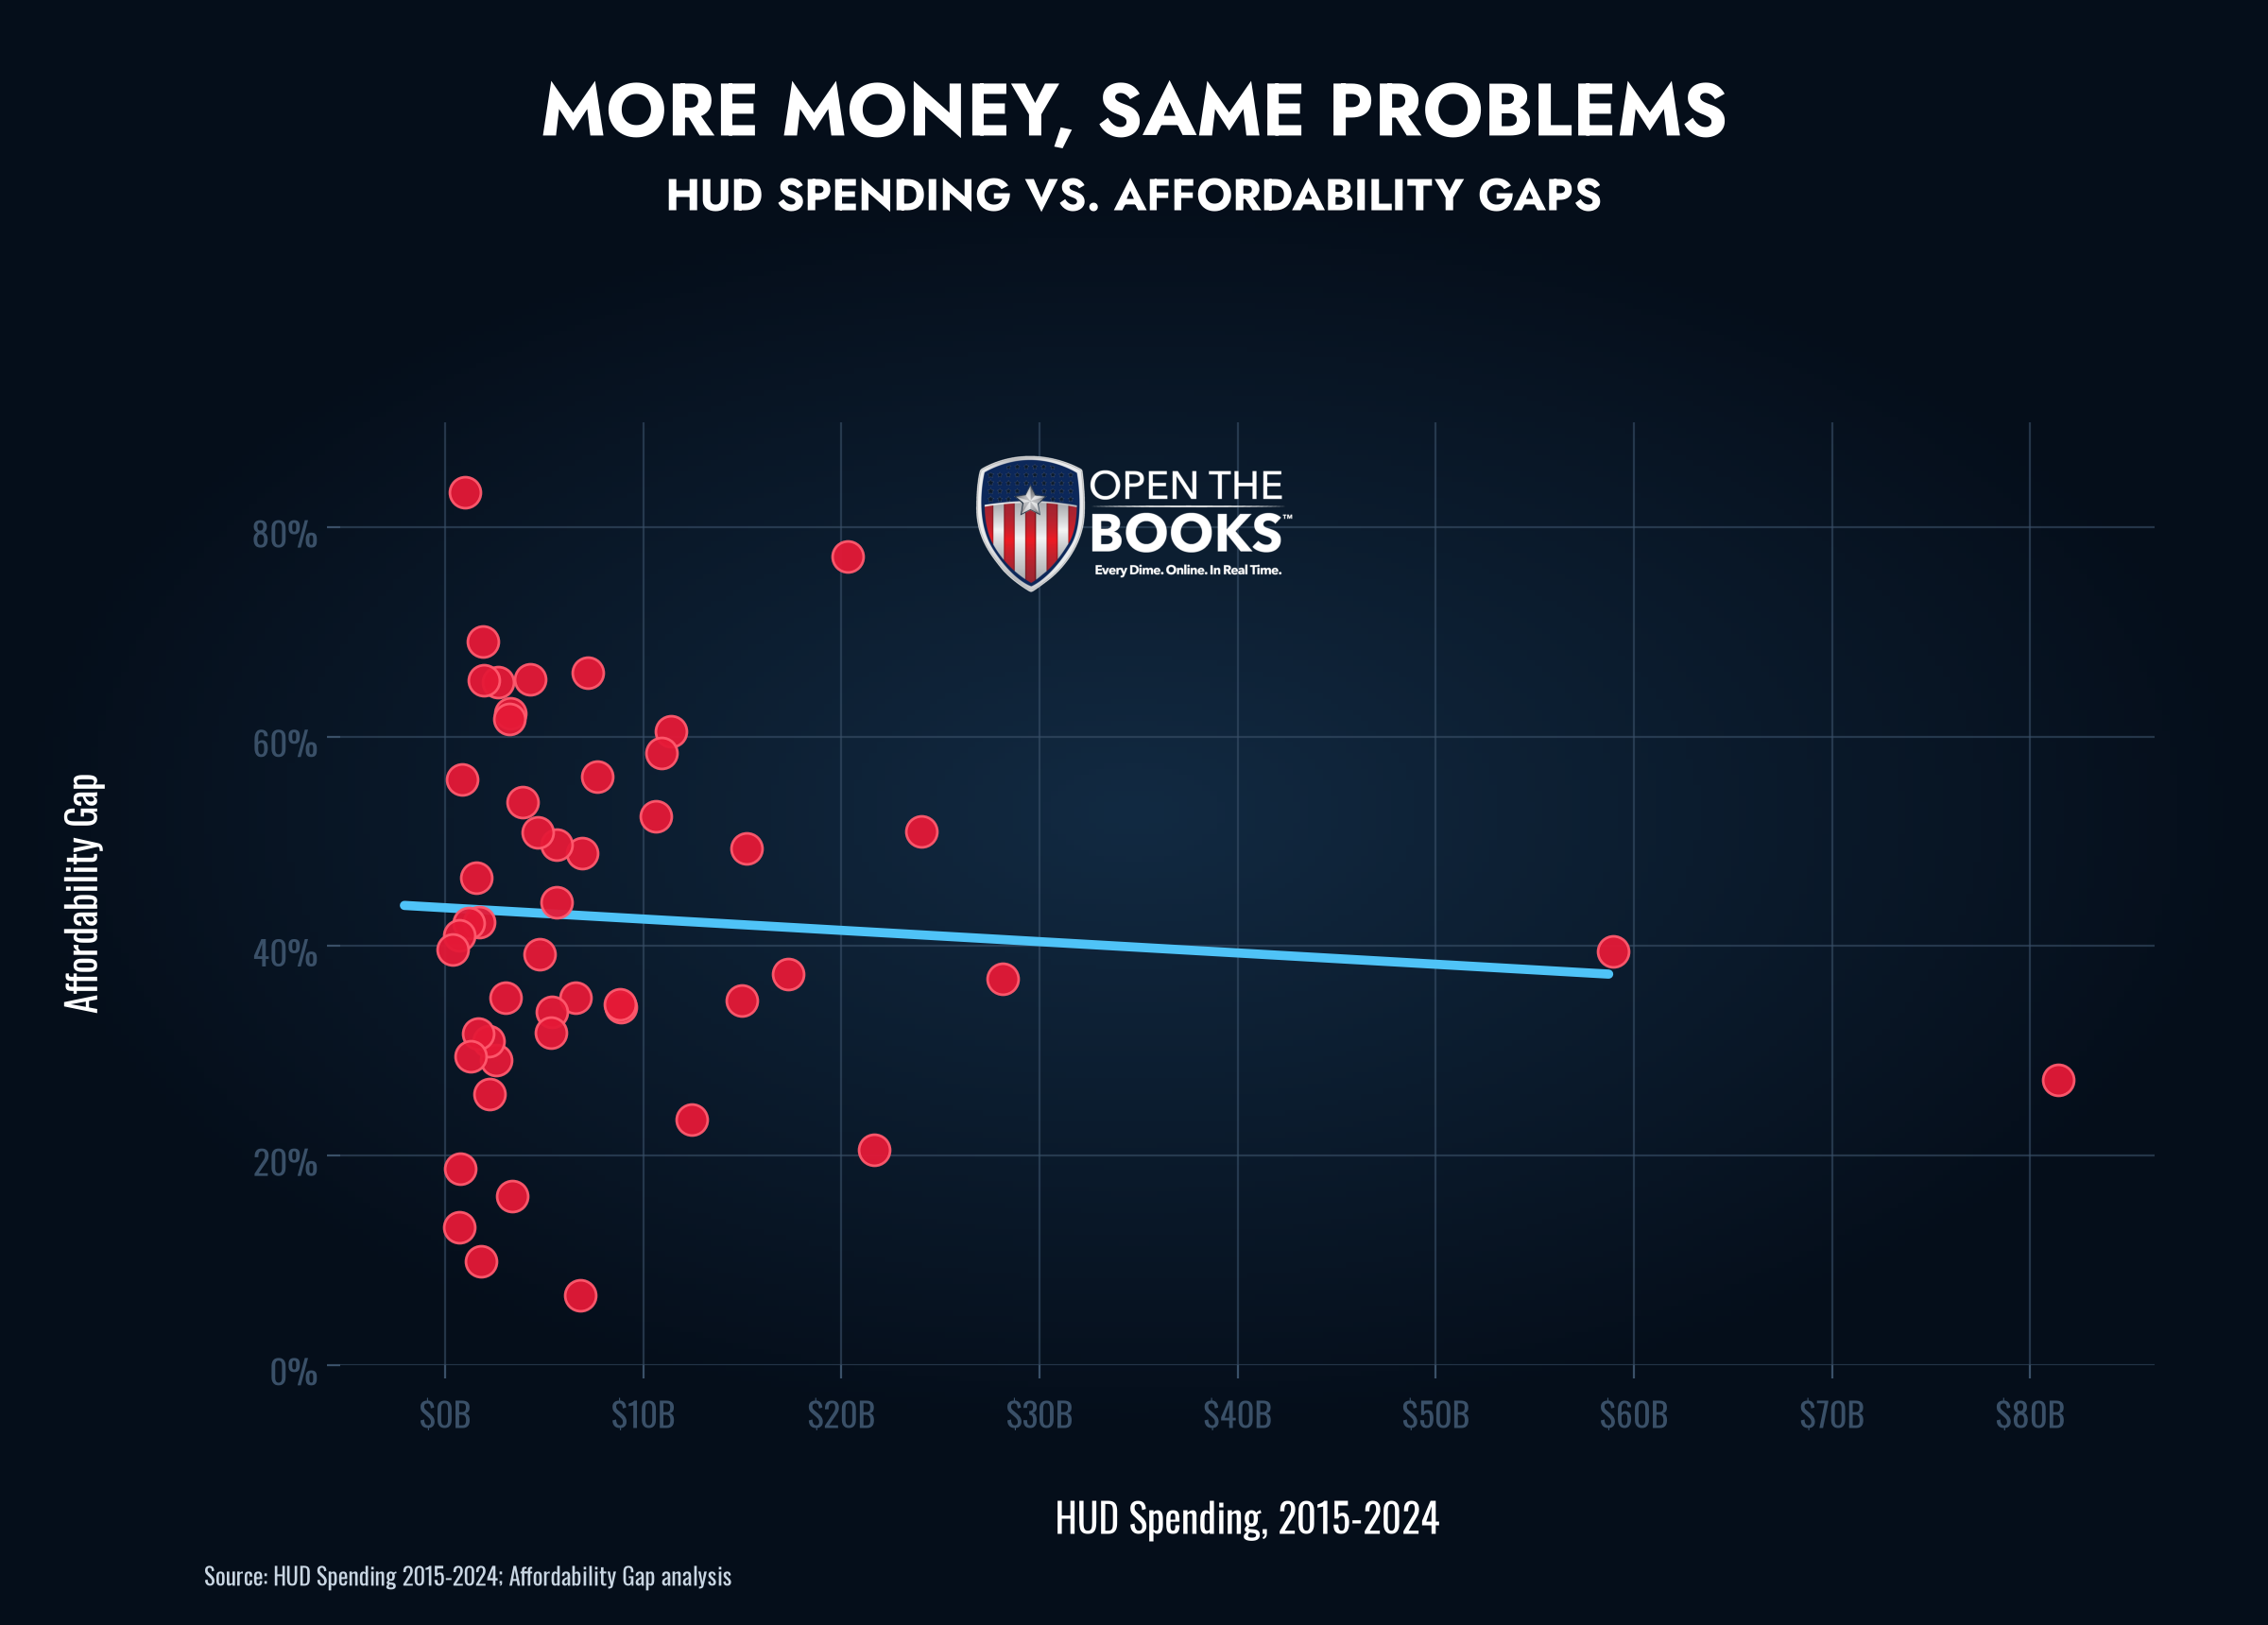
So did all this spending have any meaningful relationship with lower Affordability Gaps? Average home prices outran household incomes everywhere, but did taxpayer money help keep the gap a bit tighter? In a word, no; not when looking at total spending per state versus the Affordability Gap in that state over the decade-long timeline.
Each point below represents the Affordability Gap in a given state, while its position along the X-axis represents how great the investment was from HUD. With a naked eye, we can spot California all the way on the right-hand side of the chart.
When we draw a trendline through the data and run a regression analysis, the R-squared value is 0.0079. That value measures the relationship between the two datasets. In laymen’s terms, the relationship is exceptionally weak. Only 0.79% of the reason for a lower Affordability Gap could reasonably be attributed to HUD spending.
In statistical terms, virtually none of the variation in the Affordability Gaps is explained by HUD pouring hundreds of billions of dollars into the states. It’s about as meaningful as random noise in the data; in this case it suggests there are other key variables driving virtually all of the variation.
It would be reasonable to argue that a raw-dollar comparison is insufficient to draw any conclusions. While California and New York are outliers in terms of gross expenditure by HUD, they’re also large, populous states with population-dense, major metropolitan areas. The investment here might not be comparable to a state like Idaho simply due to the huge difference in populations.
So, we broke down the HUD spending on a per-capita basis. For this analysis, it’s important to ensure the year of the spend matches the year the population was measured. Using 2024, HUD spending per capita in each state ranged from $508.77 up to $3,940.01. Massachusetts is the outlier, at the top of the scale. The second-highest annual per-capita spend is about a thousand dollars less, $2,966.44 in New York.
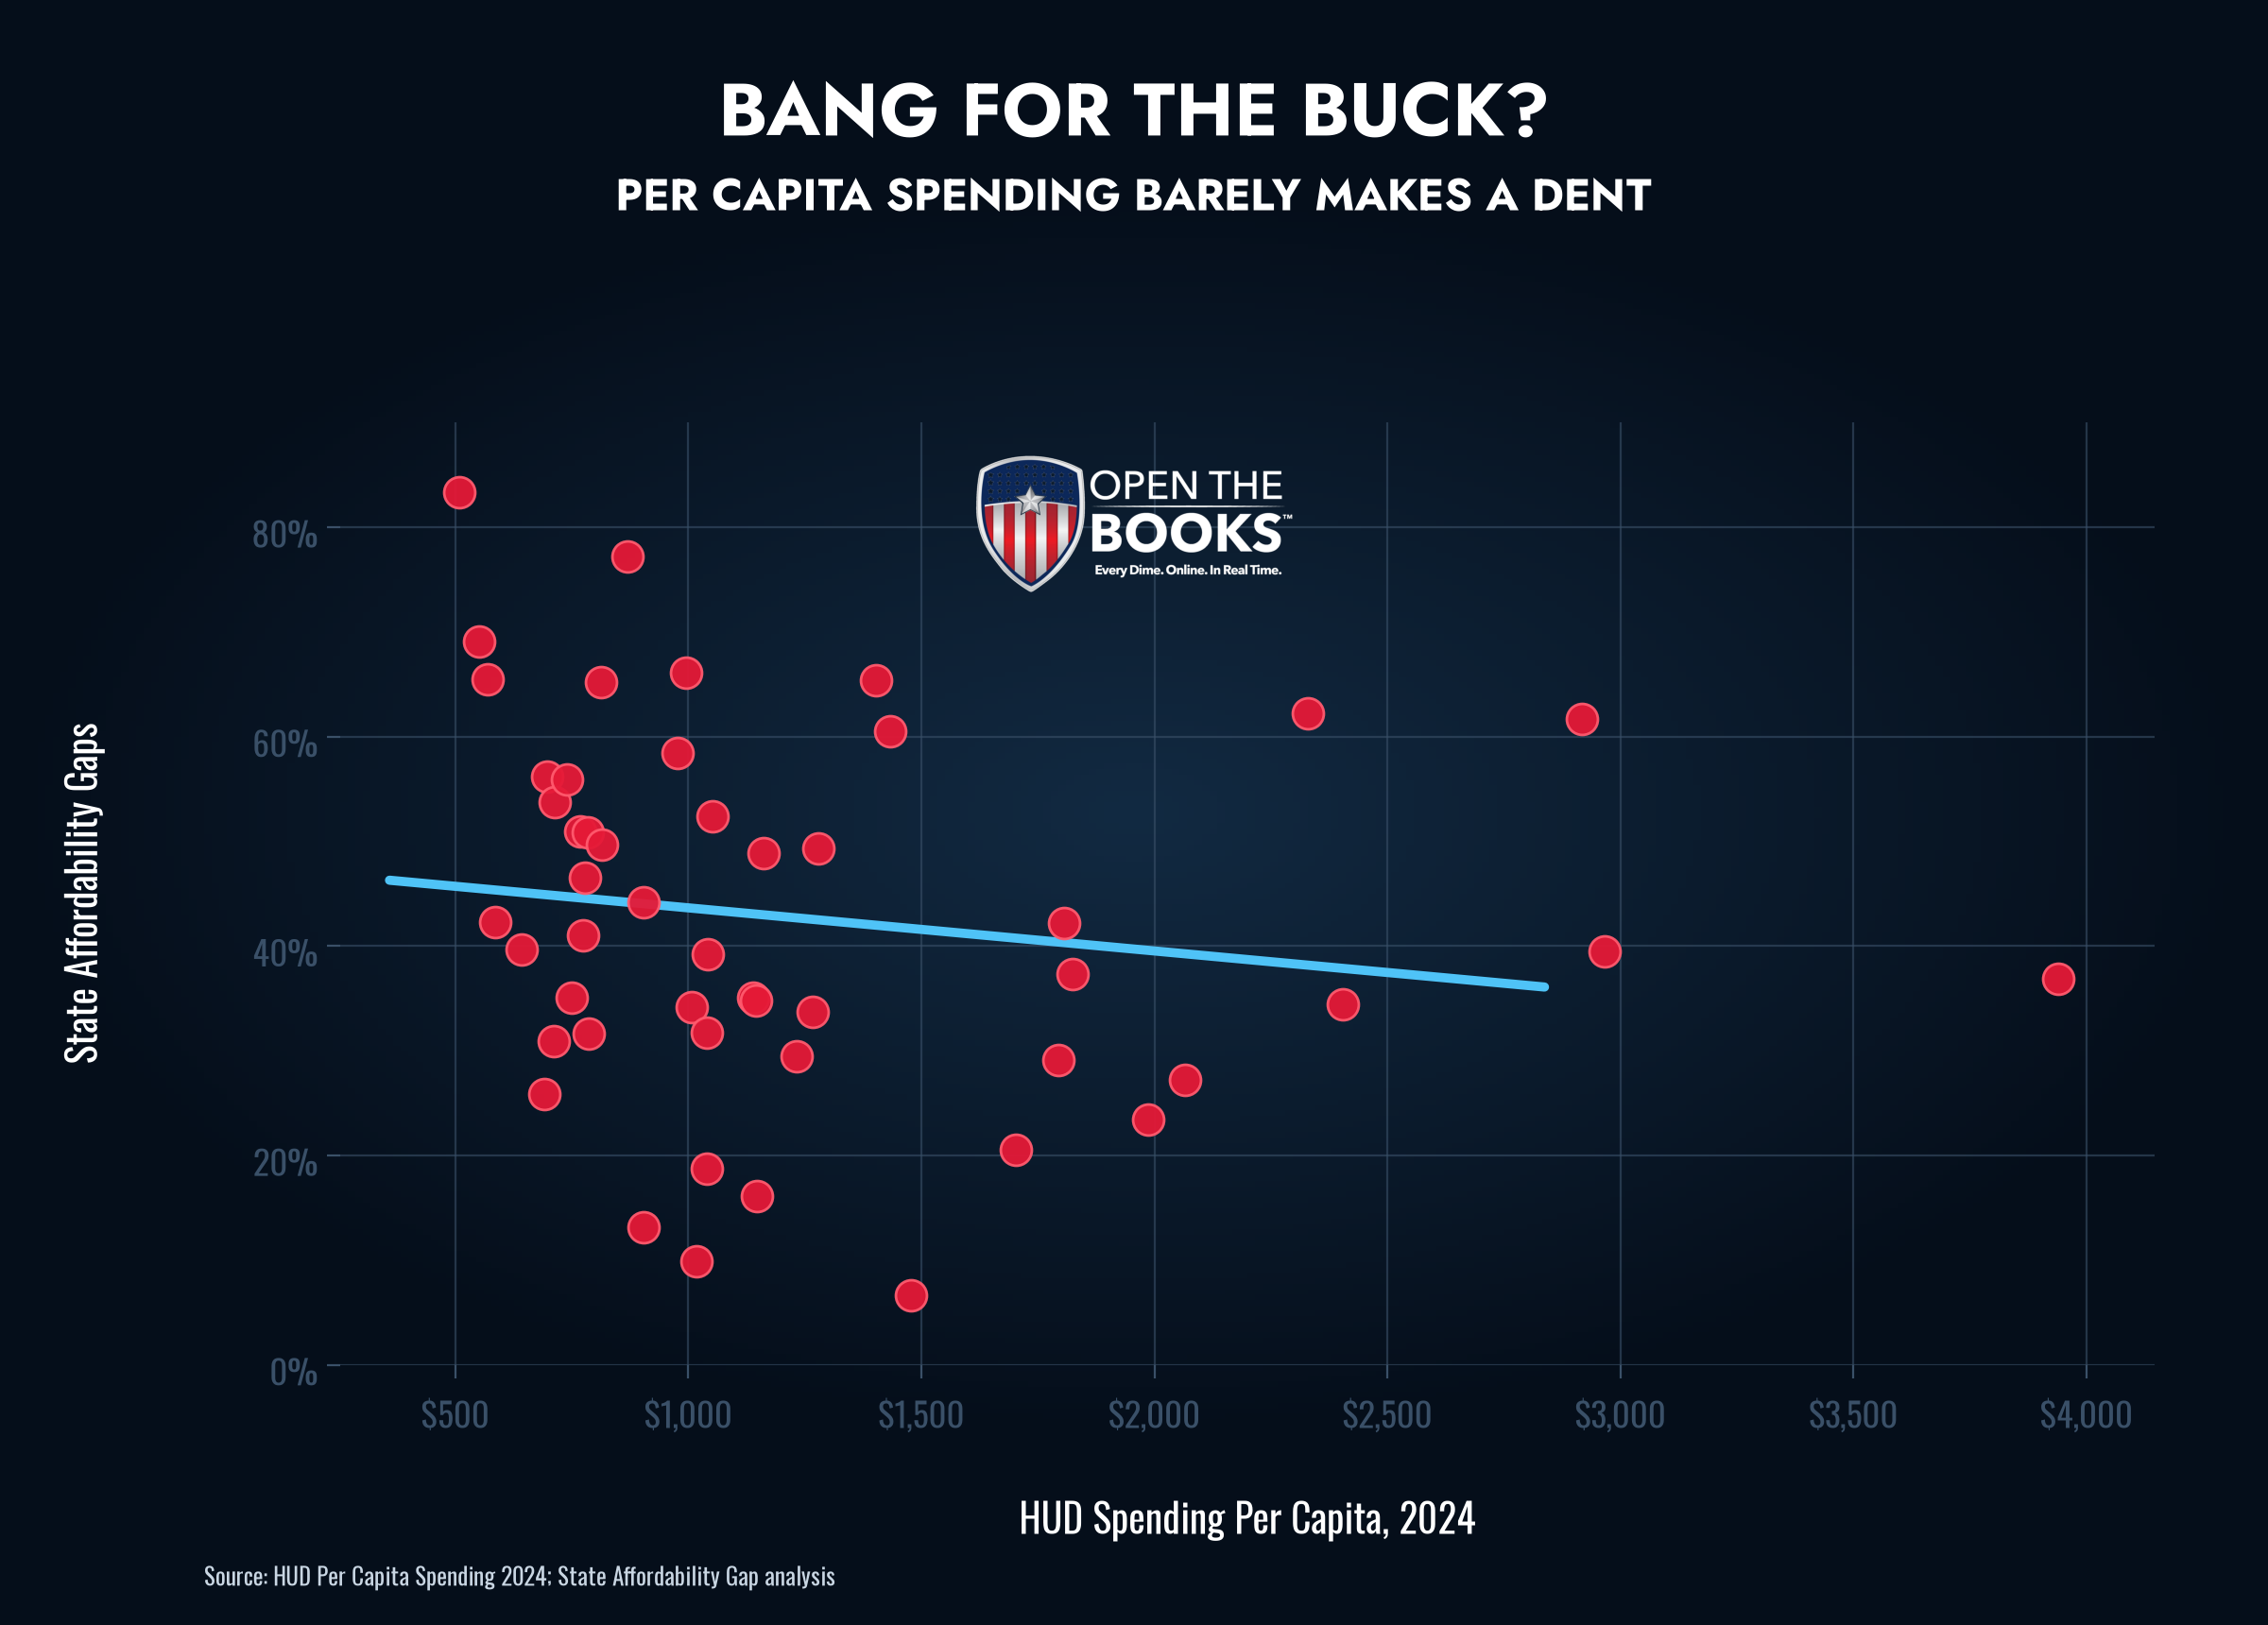
Again, the trendline shows a weak, insignificant relationship between federal spending and a reduced Affordability Gap. Only 2.75% of the variance could be accounted for by taxpayer dollars being spent by HUD, and given the number of data points, it was not statistically significant.
“The regression model indicated no statistically significant linear relationship between the variables (R² = 0.0275, p > 0.05, n = 50).”
In other words, HUD spending appears not to be curative for Affordability Gaps nor would increased spending be predictive of better outcomes.
A Deep Dive on Housing Affordability
These findings and much more are available in the latest Open the Books oversight report, Extreme Makeover: American Dream Edition?
Inside, we cover which states have the priciest and most affordable homes, track median household incomes in all 50 states, and rank states by the amount of income Americans would need to save in order to make a down payment on an average home.
If you were a median income earner and wanted to purchase an average home in your state, how much of your pre-tax income would a 20% down payment cost? If you could squirrel away 10% of your pre-tax income as savings, how long would it take you in each state to save up for that down payment?
Sneak peek: In one state, the answer is nearly a quarter of a century. It’s not the state you’re thinking of.
Also included is a deep dive into the thickets of red tape in California that slow construction of affordable units and prolong a housing shortage.
Get all of this and more by downloading the report:

Government secrecy is not an accident. It’s a strategy. Records disappear. Budgets bloat. Accountability gets buried. Open The Books forces the truth into daylight. But our data journalism is only possible thanks to support from you. Please consider making a gift to help us build on our mission to put every dime online, in real time.
It's amazing that Congress and the Senate cannot pass legislation that allows for indexing for inflation any gains from homeownership. Many homeowners (especially boomers) have "gains" that exceed the $250K (for singles) or $500K (for couples) limitation for sheltering from taxes. It's bad enough that homeowners are experiencing increasing property taxes because of their home values going up from inflation, but to have to pay federal and (usually) state taxes upon selling because of a "gain" that includes inflation, that is an additional burden that many homeowners cannot afford. Adjusting the home-sales gain to account for inflation, as is done for income, would free up quite a few larger homes for the younger generations and help stabilize the marketplace by increasing supply.
This is very valuable data...always appreciated for its comprehensive detail!
May I suggest an alternative search...especially geared toward the current generation grappling with these issues?
Consider taking a series of inexpensive Amtrak treks across the southern, midwest and northern tiers of the country.
Really SEE the vast expanses, the obvious unsung opportunities...as well as the build-up of homelessness throughout the country...which SHOULD NOT BE!
Let your mind roam beyond the 'norms' which are often designed to lead to failure and poverty.
Consider things like Resident-owned communities...similar to Employee-owned businesses, which are rather simple entities that guarantee autonomy, safety and affordability. Resident-owned communities exist for the 55+ crowd, but they are really needed for young families and others of this generation.